Direct Diagnostic Summary
Many south suburban homeowners assume that because they have comprehensive homeowners insurance, any water flooding their basement is automatically covered. Unfortunately, hundreds of homeowners discover the hard way during major storm events that standard Illinois property insurance policies specifically exclude water and sewer backups unless a dedicated endorsement has been purchased.The Critical Difference Between Flood Insurance and Water Backup Riders
One of the most financially devastating misunderstandings in residential property management is confusing overland flood insurance, standard homeowners insurance, and optional water backup endorsements. When a heavy storm hits south suburban Cook County, thousands of homeowners assume their standard insurance policy will pay for the basement flood, only to receive an immediate claim denial.
In Illinois, residential property losses are divided into three distinct statutory and policy categories:
1. Standard Homeowners Policy (HO-3 or HO-5): Standard policy forms published by the Insurance Services Office (ISO) contain a strict Water Damage exclusion under Section I. Item 1.c explicitly excludes all physical loss caused by "water or water-borne material which backs up through sewers or drains or which overflows or is discharged from a sump, sump pump, or related equipment." Standard policies only cover sudden internal plumbing breaks, such as a ruptured copper supply pipe in a finished wall.
2. Overland Flood Insurance (FEMA NFIP): A National Flood Insurance Program policy covers rising surface water that inundates dry land from outside (such as an overflowing creek, river, or surface street ponding). However, FEMA flood insurance specifically excludes water backups originating from private underground lateral failures.
3. Water Backup and Sump Overflow Endorsement (HO 04 95): An optional, affirmative policy rider that property owners must specifically request and purchase. It provides dedicated coverage for direct physical loss to real and personal property caused by sewage or water backing up through private drains or failing sump pumps.
Figure 01: Diagnostic field reference for Is Sewer Backup Covered by Homeowners Insurance in Illinois?Field Reference
Active Drainage Problem?
Speak with our south suburban dispatch coordinator
Free to call · Connected with independent local drain contractors
Free to call
No obligation
Independent local contractors
24/7 emergency dispatch
Written estimates on-site
What an Illinois Water Backup Endorsement Typically Covers and Real Costs
Insurance carriers in Illinois generally market water backup endorsements in tiered coverage increments, typically offering $5,000, $10,000, $25,000, or $50,000 in coverage for an annual premium ranging between $50 and $250. However, many homeowners mistakenly accept the minimum $5,000 rider, leaving their household budget critically exposed during an active Category 3 blackwater event.
A realistic appraisal of basement restoration costs reveals why a $5,000 policy limit is quickly exhausted:
- Immediate Emergency Wastewater Extraction & Biocide Sanitization: Under ANSI/IICRC S500 standards, contaminated wastewater must be extracted immediately and hard surfaces disinfected ($2,500–$4,500).
- Structural Dehumidification and Air Scrubbing: Operating industrial LGR dehumidifiers and HEPA air scrubbers for three to five continuous days to bring framing moisture below 15% ($1,500–$3,000).
- Mechanical Appliance Replacement: High-efficiency gas furnaces have electronic control boards and blower motors mounted low to the slab ($3,500–$5,500 to replace). Water heaters whose burners or gas controls are submerged must be condemned and replaced ($1,600–$2,400).
- Finished Basement Rebuild: Removing two feet of contaminated drywall (flood cut), excising wet fiberglass insulation, and reinstalling subfloor, flooring, and millwork ($8,000–$18,000+).
Total claim expenses for a finished basement easily reach $18,000 to $30,000, making a $25,000 or $50,000 endorsement limit a vital financial safeguard.
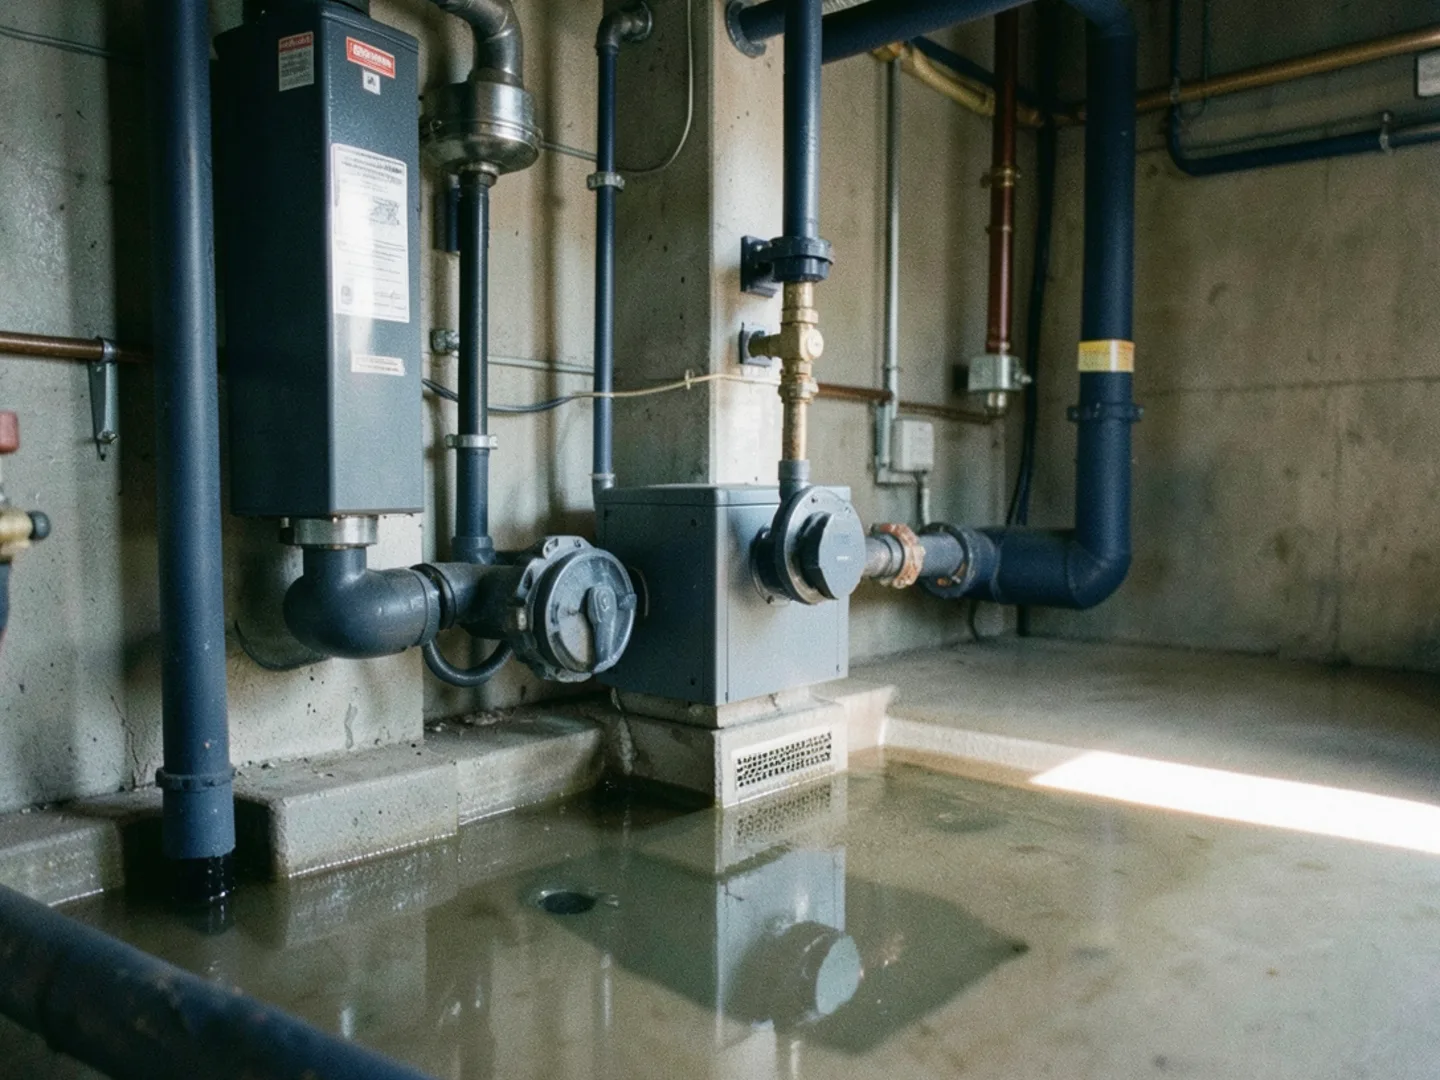
Figure 02: Diagnostic field reference for Is Sewer Backup Covered by Homeowners Insurance in Illinois?Field Reference
Essential Steps to Document Sewage Damage for Your Adjuster
When filing an emergency water backup claim with your carrier, thorough, contemporaneous evidence collection is the single most important factor determining whether your claim is accepted and settled fairly:
1. Photograph High-Water Marks Before Extraction: Take wide-angle establishing shots of every impacted room. Place a measuring tape or ruler against structural walls, baseboards, and furniture to prove water depth.
2. Preserve Damaged Mechanical Equipment: Insurance adjusters reserve the right to inspect flooded water heaters, furnace components, washers, and electronics. Do not allow junk removal teams to haul appliances away to the landfill before the adjuster has completed an in-person inspection.
3. Obtain an Itemized Contractor Invoice with Causation Details: Insurance adjusters demand proof that the event was a true drain backup rather than excluded foundation seepage. Ensure your independent sewer rodding invoice explicitly specifies: "Dispatched for active basement wastewater backup; accessed main sewer lateral; cleared dense tree root obstruction at 48 feet; restored free gravity flow to municipal main."
4. Maintain an Itemized Inventory of Personal Contents: Create a spreadsheet listing ruined electronics, furniture, clothing, and tools, detailing manufacturer names, model numbers, approximate age, and original purchase cost.
Figure 03: Diagnostic field reference for Is Sewer Backup Covered by Homeowners Insurance in Illinois?Field Reference
Why Claims are Denied: Maintenance Neglect vs. Sudden Surcharge
Insurance adjusters are legally trained to distinguish between covered sudden occurrences and excluded policy conditions under Illinois Department of Insurance guidelines. The two most common causes of claim denial are:
1. Foundation Seepage Exclusions:
If storm runoff saturates exterior soil and water enters the basement by seeping through porous concrete block, wall settling cracks, or the cove joint between the slab and footing, insurance companies will classify the loss as foundation seepage, which is excluded under virtually all home policies and backup riders. Documenting that water emerged strictly from a floor drain or toilet bowl prevents this denial.
2. Lack of Maintenance Allegations:
Insurers may argue that a homeowner allowed chronic, slow sewer leaks to rot subflooring over months without corrective action, categorizing the loss as gradual wear-and-tear. Having records of periodic mechanical sewer rodding or a clean follow-up camera inspection proves that the homeowner practiced diligent utility maintenance and that the backup was a sudden, unforeseen blockage.
Figure 04: Diagnostic field reference for Is Sewer Backup Covered by Homeowners Insurance in Illinois?Field Reference
Expert Insights: How to Challenge a Disputed Claim or Underpaid Settlement
If your insurance carrier denies your water backup claim or offers a settlement that fails to cover the realistic cost of professional biohazard remediation and mechanical replacement, Illinois property owners have strong statutory consumer protections:
1. Review the Written Denial Letter Against Your Policy Jacket:
Under Illinois insurance law, carriers must cite the exact policy language, section number, and exclusion relied upon in their written denial letter. Compare this citation directly against your declarations page and endorsement riders.
2. Invoke the Policy Appraisal Clause:
Virtually all standard Illinois homeowners policies include an Appraisal Clause. If you and the insurance company disagree on the scope or dollar value of the loss, you can demand an independent appraisal. Each party selects a competent, independent appraiser, and the two appraisers choose an impartial umpire to establish a binding settlement decision.
3. File an Administrative Consumer Complaint with the IDOI:
The Illinois Department of Insurance (IDOI) investigates improper claims practices under Title 50, Part 919 of the Illinois Administrative Code. Filing a formal complaint triggers a mandatory state inquiry, requiring the insurance carrier to provide a detailed written justification of its claims handling and payment calculations.
Illinois Home Insurance Water Loss Coverage Comparison
Comparative mechanical metrics and local south suburban cost drivers.
| Loss Scenario | Standard Home Policy | Water Backup Rider | Flood Policy (NFIP) |
|---|---|---|---|
| Main Sewer Line Backs Up via Floor Drain | EXCLUDED | COVERED (up to limit) | EXCLUDED |
| Sump Pump Fails During Power Outage | EXCLUDED | COVERED (up to limit) | EXCLUDED |
| Creek Overflow Enters Basement Windows | EXCLUDED | EXCLUDED | COVERED |
| Burst Second-Story Copper Water Pipe | COVERED | Not Applicable | EXCLUDED |
| Water Seeps Through Basement Wall Cracks | EXCLUDED | EXCLUDED | EXCLUDED |
Cited Research & Regulatory Authorities
The technical guidance and municipal standards referenced in this guide are informed by official state, regional, and industry publications:
- Homeowners Insurance Consumer Guide to Water Damage · Illinois Department of Insurance (IDOI)
- Understanding Water Backup Coverage Options · Insurance Information Institute (Triple-I)
- National Flood Insurance Program Policy Definitions · Federal Emergency Management Agency (FEMA)